Q1 2026 Market Insights
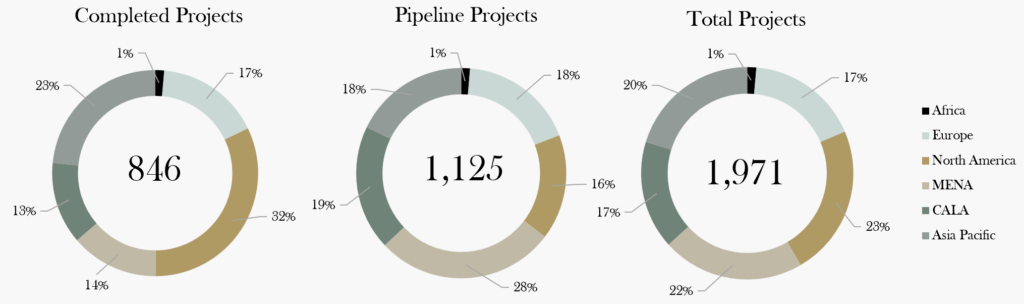
Q1 2026; The branded residential sector started 2026 on a confident note, adding 85 projects in Q1 – 82 in the pipeline and 3 newly completed projects – bringing the global total to 1,971 developments. Of those, 846 are completed and 1,125 remain in the pipeline. The pipeline of projects equates to 57% of the total number of completed and pipeline developments, reinforcing the market’s continued growth trajectory.
Hospitality brands lead, lifestyle follows; Hotel brands account for 81% of Q1 additions, with Marriott and Accor leading all parent brands, followed by Hilton, Wyndham, IHG, Kerzner International and Radisson Hotel Group. The remaining 19% is made up of non-hotel brands, led by Design brands such as YOO and Pininfarina at 40%, while Fashion, F&B, and Entertainment each account for 13%. Luxury continues to dominate with 57% of new additions, followed by Upper Upscale at 27%, confirming that, for now, this sector continues to be concentrated at the luxury end of the market.
Resorts regain momentum, standalone projects continue to expand; Mirroring Q4 2025’s resort-led growth, Q1 2026 is once again weighted toward resort destinations, accounting for 51% of new signings, compared with 36% in urban locations and 13% in urban-resort settings. After several years of urban-led growth, the market appears to be shifting. Co-Located developments lead by development type at 45%, ahead of Standalone (36%) and Integrated (19%) projects. The same ranking is reflected in the cumulative global market, where Co-Located accounts for 42% of all developments, followed by Standalone (32%) and Integrated (26%).
A more balanced regional picture – with MENA still setting the pace; MENA leads Q1 growth with 39% of all new projects, followed by CALA (18%), North America and Europe (15% each), APAC (11%), and Africa (2%). Within MENA, the UAE accounts for 58% of the region’s Q1 additions, followed by Egypt (24%) and Saudi Arabia (18%). CALA’s growth is led by Mexico (27%), with both the Dominican Republic and Brazil contributing 20% each. North America continues to be overwhelmingly driven by the United States, while Europe’s activity is more evenly distributed, with France and Italy each accounting for 23%, followed by Greece, Turkey, and Albania at 15%. In APAC, Thailand represents 33% of new projects, while China, Vietnam, Malaysia, the Maldives, India, and Kyrgyzstan each account for 11%.
Across the global inventory of 1,971 completed and pipeline projects, the market remains relatively balanced among its three leading regions. North America holds the largest share at 23%, closely followed by MENA (22%) and APAC (20%). Europe accounts for 17% of global projects, CALA for 16%, and Africa for the remaining 1%. The pipeline alone, however, tells a different story: MENA leads with 28% of all pipeline projects, followed by CALA (19%), with both Europe and APAC accounting for 18% each. This provides a clear indication of where future market growth is being concentrated.
This Quarter’s Market Spotlight – Leading Parent Companies Per Region; This quarter’s spotlight turns to the leading players by parent company in each region, revealing how competitive dynamics vary across global markets. Each region tells a different story about who is driving branded residential growth.